Content developed with the assistance of AI tools and reviewed by the author.
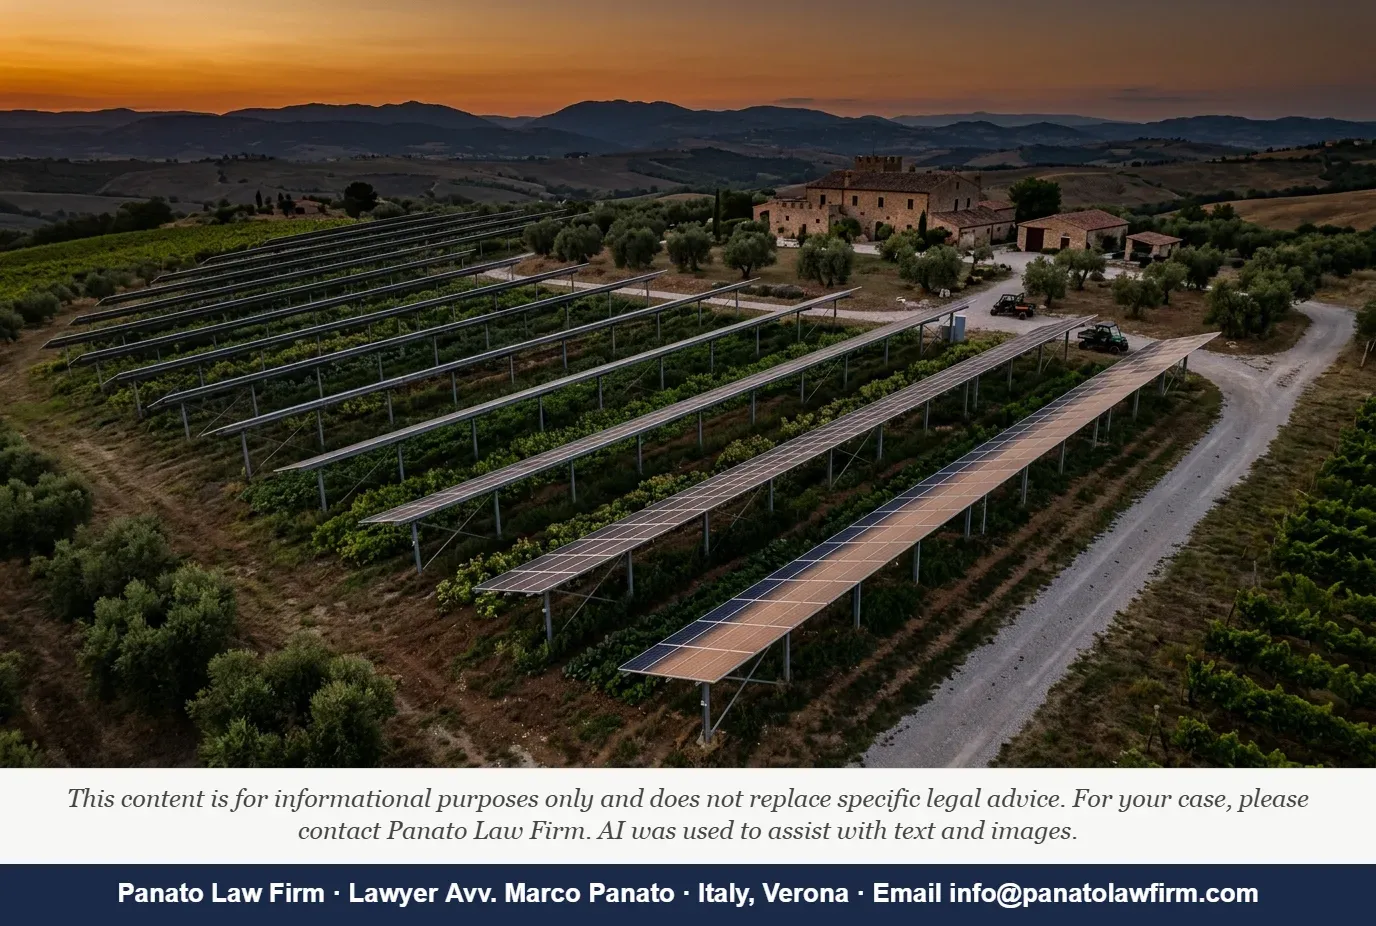
What Australian pension funds, infrastructure managers and foreign buyers miss in Italian agrivoltaic due diligence — from grid queues to Golden Power notifications and pre-emptive farmer rights
Are you buying an Italian agrivoltaic project as a foreign company, and wondering whether your deal can actually close? The short answer is: yes — but five distinct legal failure-points can kill the timeline, void the title transfer, or strip the subsidy after financial close. Each one is avoidable. None of them shows up in the standard information memorandum.
Italy's agrivoltaic pipeline stands at 12.5 GW as of Q2 2026, up from 2 GW in 2023. On 18 June 2026, the Italian Ministry of Environment and Energy Security signed the final FerX Decree, which builds upon and significantly expands the transitional support mechanism established by the Ministerial Decree of 30 December 2024. For Australian superannuation funds and infrastructure managers, this is precisely the moment at which deal velocity is highest and legal caution is lowest.
That asymmetry is dangerous. Parliamentary motions calling for a cap on foreign ownership of Italian agricultural land are now in circulation following a September 2026 controversy in Tuscany involving a foreign-linked project. The political temperature around overseas buyers of Italian farmland is rising, and it intersects with a regulatory framework that already imposes hard legal obligations — five of which are routinely missed.
Every Italian agrivoltaic project needs two parallel approvals: an environmental and building permit (autorizzazione unica) and a separate grid-connection authorisation issued under ARERA (Italy's energy regulatory authority) procedures. Most buyers focus on the first and assume the second follows. It does not.
Italy has approximately 70 GW of solar capacity awaiting grid connection, with median queue times of 4 to 6 years. The queue represents roughly six years of deployment at the current pace. Italy's Energy Decree entered into force on 21 February 2026, and ARERA has 180 days from that date to update the grid-connection rules, introducing competitive and non-discriminatory procedures — known as "open season" — for the allocation of capacity slots. Existing connection solutions that have been issued but not validated by the grid operator for projects not yet authorised will lose their effectiveness once the new ARERA rules are published; however, projects that are already fully authorised are safe, and their connection rights are preserved.
The practical consequence: a project that the seller presents as having a 90-day permitting window may sit in a four-to-six-year grid queue before it earns a single euro. The grid-connection position — its queue number, the date of the formal connection request, and the status of the Terna (Terna S.p.A., Italy's transmission system operator) technical study — must be verified independently before any preliminary sale contract is signed. Buying a project without a validated connection solution is buying a piece of land with a permit but no revenue.
Italy's fast-track permitting designation sets a 90-day approval cap and mandates that at least 70% of the land remains cultivable, ensuring food security. This figure comes directly from the land-use condition introduced alongside the Decreto Agricoltura (Law Decree No. 63/2024, converted into Law No. 101 of 12 July 2024), which banned solar PV installations on agricultural land with effect from 16 May 2024. Agrivoltaic systems are the principal exemption — but that exemption carries a continuous compliance obligation, not a one-time threshold.
Regional authorities verify agricultural yield annually, and developers who fail to meet the 70% yield requirement face retroactive permit revocation and fines of up to €50,000 per hectare, plus loss of feed-in tariff benefits.
The cadastral trap works like this. Italian land is registered in the national land registry (catasto) with a designated agricultural use. If the installed panel array reduces productive agricultural activity below the 70% threshold — through shading density, access restrictions, or simple mismanagement of the agricultural operator — the land's cadastral classification can be reclassified from agricultural to industrial. That reclassification triggers a cascade: higher property taxes (IMU), loss of agricultural entrepreneurial tax treatment, and, crucially, the GSE (Italy's energy services manager, Gestore dei Servizi Energetici) may terminate the CfD support contract.
Unlike in most common-law countries, where a planning or zoning classification is typically a one-time decision reviewed only on application, Italian cadastral classification is actively monitored by regional agricultural authorities and can be revised unilaterally during the project's operational life. An Australian fund accustomed to long-dated infrastructure assets — where planning approval is a sunk cost — needs to treat the 70% agricultural yield requirement as a recurring performance covenant, not a development condition.
Yes — and this is the single most under-disclosed risk in agrivoltaic information memoranda directed at non-EU buyers.
Under the Golden Power Law (Decree-Law No. 21/2012, as amended), FDI clearance is mandatory for strategic company transactions in the energy, transportation, communication, health, agri-food and financial sectors. On 15 January 2026, the Italian government approved revisions to the Golden Power Law including adding "economic and financial security" among the key national interests protected.
An agrivoltaic project sits at the intersection of two covered sectors: energy and agri-food. The Golden Power Law operates on a principle of substance over form, so the creation of corporate, fiduciary or contractual investment structures will not limit its applicability if the ultimate beneficial investor falls within its scope. For a non-EU buyer — which includes Australian superannuation funds and infrastructure vehicles — notification is mandatory even for a minority stake in a project company, provided the transaction meets the relevant thresholds.
The Italian government can veto, condition, or make material recommendations with respect to the transaction if it falls within the scope of the Golden Power Law. Conditions imposed in practice have included operational restrictions, reporting obligations, and requirements to source components locally. The notification must be filed before signing, and the standstill obligation applies: closing without clearance voids the transaction.
The September 2026 Tuscany controversy — involving parliamentary scrutiny of a foreign-linked agrivoltaic acquisition — has placed the agri-food/energy intersection directly under political spotlight. Expect the government's review of non-EU acquisitions in this sector to be more intensive, not less, through at least mid-2027.
Italian law protects agricultural tenants when leased farming land is put on the market for sale. Article 8 of Law No. 590 of 26 May 1965 states that the tenant, sharecropper, settler or co-participant has the right of pre-emption — first refusal to buy — in the event of the sale of the land.
The right of pre-emption belongs to two categories in a specific order: first, the tenant farmer; then the neighbouring owner who is a farmer. These are two distinct rights of pre-emption, which operate in a subordinate manner. The landowner must notify the person entitled — by registered letter — of the preliminary sale contract, including the purchaser's name, price, and all other terms. The farmer must exercise the right within 30 days of receiving the communication.
The danger for a foreign buyer: if the seller fails to notify, or notifies incorrectly, the eligible tenant or neighbour can exercise a right of redemption (riscatto) after the notarial deed of sale is executed. They pay the same price you paid, and the title passes to them. The sale is not merely voidable; it is overridden. The right of pre-emption belongs primarily to tenants who have been cultivating the land continuously for at least two years. The tenant must cultivate the land directly, must not have sold other agricultural land in the previous two years, and must comply with the size limits set out in legislation.
Ubi jus incertum, ibi jus nullum — where the right is uncertain, there is no right at all. The only safe course is to obtain a formal waiver of pre-emption rights from every eligible farmer before the notarial deed of sale is executed. This is the step that sellers, anxious to close, most commonly omit or rush.
In our files at Panato Law Firm, the most common mistake is a seller who confirms there is "no tenant" on the land — which is legally irrelevant. The correct question is whether any person has cultivated the land for two or more years, under any arrangement, whether or not a written lease exists. Oral cultivation agreements, family arrangements, and informal sharecropping are all sufficient to trigger the pre-emption right.
The FerX contract-for-difference framework administered by the GSE is the revenue backbone of every bankable Italian agrivoltaic project. Buyers assume the CfD is a government guarantee. It is not a one-way instrument.
The final award price, determined by the winning bid, becomes the contractual reference for the two-way contract for difference with the GSE over the 20-year support period. For installations of up to 200 kW, the GSE directly withdraws and sells the electricity, paying the award price as an all-inclusive tariff. For installations of 200 kW or more, the producer retains commercial control over the energy and settles differences with the GSE based on the Day-Ahead Market price.
The two-way structure means that when the Day-Ahead Market price exceeds the CfD strike price, the project pays the difference back to the GSE. In a period of elevated European energy prices — as seen repeatedly since 2021 — a project can find itself making net payments to the GSE rather than receiving support. Once the 20-year CfD period is concluded, if the energy support provided by the state has not been effectively reimbursed, projects are subject to a clawback mechanism — essentially a second CfD under which the GSE is entitled to buy power from the client.
The financial model must account for scenarios in which the project is a net payer to the GSE during high-price periods. Any acquisition price that assumes unidirectional CfD income is mis-valued. The EU Foreign Subsidies Regulation (Regulation (EU) 2022/2560) adds a further layer: above-threshold tenders involving non-EU public funding must be notified to the European Commission, and failure to notify can result in the Commission ordering repayment of subsidies received.
Yes. There is currently no statutory ban on foreign ownership of Italian agricultural land, and the Italian Constitution does not distinguish between domestic and foreign investors in property rights. However, three overlapping mechanisms constrain non-EU acquisition in practice: Golden Power notification (mandatory for non-EU buyers, with potential for government veto); the pre-emptive purchase rights under Article 8, Law 590/1965 (which must be extinguished before closing); and the emerging parliamentary debate on a foreign ownership cap — which, if enacted, could affect projects in the permitting phase at the time of any transitional provisions.
The fast-track permitting designation introduced under Legislative Decree 190/2024 sets a 90-day approval cap, reducing bureaucratic delays that historically stalled projects. That cap applies to the environmental and building authorisation track for qualifying projects in designated agrivoltaic zones. It does not apply to the grid-connection authorisation, which follows a separate ARERA-regulated process and which — as set out above — can run for four to six years in the current queue environment.
Buyers should therefore plan for a total project development timeline of 18 to 36 months from land acquisition to energisation, assuming a clean permit position and a validated grid-connection slot. Projects that lack a validated connection solution at signing face materially longer timelines.
The Golden Power notification triggers a 45-day review period, extendable by a further 45 days if the government requests additional information. That is the statutory window. In practice, for non-EU buyers in the energy/agri-food intersection, engage for at least 90 days in your deal timetable. Any heads of agreement should make Golden Power clearance a condition precedent, not a post-completion obligation.
The most consistent pattern we see is a foreign buyer who receives an information memorandum structured around the permitting timeline and the CfD tariff, and signs heads of agreement before commissioning a land registry search (land registry search, visura catastale) or a title investigation. By the time Italian counsel identifies an unextinguished pre-emption right or an unvalidated grid-connection solution, the exclusivity period has already imposed commercial pressure to close. Build the five checks outlined here into the pre-exclusivity phase, not the due diligence phase that follows it. The cost of doing so is measured in legal fees. The cost of not doing so is measured in the deal price.
"Real estate cannot be lost or stolen, nor can it be carried away." Franklin Roosevelt said this of property as an asset class. He had not encountered an unextinguished Italian agricultural pre-emption right held by a neighbouring farmer who will not waive it at any price.
Before heads of agreement are executed, instruct Italian counsel to complete a five-point pre-exclusivity check: (1) obtain the current grid-connection queue status from Terna directly; (2) commission a land registry search on every parcel and cross-check cadastral classifications against the project's panel layout; (3) identify every person who has cultivated any parcel in the last two years and obtain formal pre-emption waivers; (4) confirm whether the acquisition vehicle triggers Golden Power notification in both the energy and agri-food sectors under Decree-Law No. 21/2012 as amended by Law No. 4 of 15 January 2026; and (5) model the two-way CfD exposure across three energy-price scenarios.
Panato Law Firm, led by Avv. Marco Panato in Verona, Italy, advises international clients — including Australian and other foreign investors — on Italian renewable energy transactions, agricultural land acquisitions, and Golden Power procedures. To discuss your agrivoltaic due diligence, write to info@panatolawfirm.com or call +39 045 5867034. The firm advises on Italian law and works with local counsel in the reader's jurisdiction where cross-border coordination is required.
Can an Australian company be blocked from buying an Italian agrivoltaic project on Golden Power grounds?
Yes. As a non-EU buyer, an Australian entity must notify the Italian government before completing an acquisition in a company with energy or agri-food activities. The government can impose conditions or veto the transaction entirely. Failure to notify voids the transfer and can result in administrative sanctions. Build a minimum 90-day Golden Power clearance window into any deal timetable.
What happens if the tenant farmer's pre-emption right is not extinguished before completion?
If the seller fails to notify eligible farmers correctly, any qualifying tenant or neighbouring farmer can exercise a right of redemption — paying the purchase price you paid and taking title in your place. This right exists even after the notarial deed of sale is executed. The only protection is a formal written waiver obtained from every eligible person before completion.
Does the FerX CfD guarantee income for the full 20-year period?
No. The FerX CfD operates in both directions. When the Day-Ahead Market price exceeds the awarded strike price, the project pays the difference to the GSE. In high-price periods, this means the project is a net payer, not a net recipient, of CfD flows. A financial model that projects unidirectional subsidy income throughout a 20-year period is incomplete. Additionally, a residual clawback mechanism can apply at the end of the CfD period if cumulative state support has not been offset by above-strike market periods.
HREFLANG BLOCK:
Editorial Team — Panato Law Firm Staff