Why every US acquirer of an Italian bank or insurer now faces a multi-level regulatory cascade — and why your current SPA template is not built for it
LANG: English (en) · AREA: Foreign Direct Investment & M&A · TYPE: Case note (court decision) · MODEL: Sonnet 5 · SEO 84/100 · Flesch Reading Ease 32
ABSTRACT: Law No. 4 of 15 January 2026 rewrote the rules for any foreign acquisition of an Italian bank, insurer or credit institution. It introduced a mandatory sequencing rule: Italian golden power review cannot begin until both the European Commission and the European Central Bank have concluded their own assessments. For a US acquirer, that means the closing date is now hostage to the slowest regulator in a three-stage cascade — and most standard purchase agreement templates from 2025 are not written to handle it.
The most expensive mistake a US acquirer makes in Italian financial-sector M&A is drafting the deal on an American timeline. The assumption is that regulatory approvals run in parallel, like Hart-Scott-Rodino clearance alongside a Federal Reserve review. In Italy, since 21 January 2026, they do not. They run in sequence. The Italian government cannot act until Brussels and Frankfurt have finished. And neither Brussels nor Frankfurt has a fixed deadline that matches your board's closing expectations.
What Law 4/2026 actually does to your deal timelineLaw No. 4 of 15 January 2026 represents Italy's legislative response to the European Commission's infringement proceedings opened in the wake of the aborted UniCredit/Banco BPM merger. It materially reshapes the procedural framework for transactions in the financial, credit and insurance sectors.
The reform introduces a sequencing rule that subordinates the Italian government's golden power review to prior decisions of the European Commission and the European Central Bank. In plain terms: a US private equity fund or bank holding company buying into an Italian lender must first obtain EC merger clearance under the EU Merger Regulation, then wait for ECB prudential approval under the Single Supervisory Mechanism, and only then will Italian authorities exercise — or decline to exercise — their golden power. The new rules address the Commission's concerns by establishing procedural safeguards: the EC and the ECB must conclude their own assessments before Italy can act.
The golden power proceedings being postponed until after the proceedings before the Commission or the ECB has a material effect on timing. The FDI screening procedure ordinarily takes 45 days, extendable. Add EC Phase I review (25 working days, extendable to Phase II at up to 90 working days) and ECB prudential assessment (typically 60 to 90 working days, with possible extensions), and a transaction that your investment committee modelled as a nine-month close could realistically run to twelve months or longer — before the Italian stage even starts.
How long does Italian golden power clearance take for a bank deal in 2026?Under the pre-reform regime, a notified transaction triggered a 45-day Italian review window that could be extended once. That window still exists but it no longer starts running until the EU-level reviews are complete. EC Phase I alone takes a minimum of 25 working days. If the Commission opens a Phase II investigation — as it did in major banking deals — the EC stage alone can consume five to six months. The ECB's Significant Institution acquisition assessment runs under Article 22 of Directive 2013/36/EU (the Capital Requirements Directive) and carries a 60-working-day assessment period, extendable by a further 30 working days if the ECB requests additional information. These EU stages do not formally run in parallel under the new sequencing rule: Italian review follows rather than accompanies them. A realistic combined timeline for a transaction triggering all three reviews is twelve to eighteen months from signing to close. Budget accordingly when negotiating your long-stop date.
Does the new sequencing rule reduce the risk that Italy will block the deal?No. This is the point that most client-facing alerts miss. While the sequencing rule requires Italian authorities to wait for decisions from the European Commission and the European Central Bank before imposing conditions or blocking transactions, it may lengthen transaction timelines and create new considerations for deal structuring, conditionality, and regulatory risk. Governmental discretion at the Italian stage is fully preserved. The Italian executive retains every power it held before Law 4/2026: it may still approve unconditionally, approve with conditions, or block. The reform elevates "national economic and financial security" to the status of a recognised essential interest for the purposes of the government's intervention powers. That new ground for intervention is broader, not narrower, than the pre-2026 "national security" formulation. Italy's response to the infringement proceedings was procedural, not substantive.
History should concentrate the mind. In April 2025, the Italian government granted golden power clearance subject to conditions binding on the merged bank, including a five-year floor on the loan-to-deposit ratio, restrictions on the project finance portfolio in Italy, a sovereign bond commitment for Banco BPM's asset manager Anima SGR, and a requirement that UniCredit discontinue its Russian operations within nine months. UniCredit ultimately abandoned the transaction in July 2025, after an Italian administrative court substantially upheld the government's decision. A longer process did not produce a lighter touch.
The SPA drafting trap nobody is fixing fast enoughThis is where the practical damage concentrates, and it is the element most deal-team alerts gloss over.
A standard 2025-vintage US acquisition agreement — whether drafted under New York or Delaware law — typically contains a material adverse change definition that carves out changes in applicable law as not constituting a MAC. The logic is sensible for domestic US transactions: regulatory change is systemic, not target-specific. But that carve-out does not serve a buyer who needs to argue that a six-month ECB backlog causing the Italian review to push past the long-stop date is a basis for termination or price renegotiation.
Under Law 4/2026, the delay is not caused by a change in the target's business. It is caused by regulatory sequencing that was, strictly speaking, already law on the date of signing — it entered into force on 21 January 2026. A "change in applicable law" MAC trigger will therefore not fire at all for any deal signed after that date. The delay is the new normal, not a change from it.
The fix is specific: regulatory clearance conditions in the SPA must be structured around each individual clearance separately — EC, ECB, Italian golden power — each with its own milestone date and its own walk-right if the relevant authority has not acted within an agreed outer limit. Hell-or-high-water clauses must distinguish between the obligation to pursue clearance and the obligation to accept any conditions imposed. A buyer's obligation to use "reasonable best efforts" to obtain Italian golden power clearance should expressly exclude accepting conditions that materially alter the target's business model, particularly lending-portfolio or liquidity commitments of the kind seen in the UniCredit case.
Do intragroup restructurings trigger golden power notification in Italy?Yes — with important nuance introduced by recent case law. 2024 was a year marked by a further expansion of scrutiny over pledge transactions, including indirect pledges over the shares of foreign companies controlling Italian strategic assets. Then came a landmark clarification. The Council of State, in a 5 December 2025 ruling in the Cedacri case, established that creating pledges on shares of strategic companies does not require prior notification under Italian FDI regulations, unless the transaction involves an immediate and concrete transfer of control or availability of the assets.
In full: the Council of State (Italy's highest administrative court, the
Consiglio di Stato) held that the mere granting of a pledge over the shares of a strategic Italian company does not require an FDI filing when the pledge agreement provides that voting, administrative, and economic rights of the pledged shares remain with the pledgor until default occurs, provided that enforcement upon default will require a filing and thus be subject to compliance with the Italian golden power law.
This ruling — Council of State, Section IV, Judgment No. 9619 of 5 December 2025 (
Cons. Stato, Sez. IV, 5 dicembre 2025, n. 9619) — matters for two distinct audiences. For acquisition financiers, it reduces the upfront filing burden on share pledge structures provided the documentation is correctly drawn. For intragroup restructurings, the analysis remains fact-specific: if a reorganisation transfers control, even indirectly, over a regulated Italian entity, notification under Decree-Law No. 21/2012 is likely required. The Presidency of the Council of Ministers retained the ability to appeal to the Italian Court of Cassation within six months of the ruling's publication. Pending the outcome, the prudent course is to continue case-by-case assessment of share pledge agreements over Italian strategic targets.
What is "economic and financial security" as a protected interest under Law 4/2026?The legislation formally recognises "national economic and financial security" as an essential national interest. Although Italian authorities characterise this as a clarification of existing practice, the broader concept may face scrutiny under EU law, which traditionally limits restrictions on investment and establishment to genuine public security concerns.
For a US buyer, the practical consequence is exposure to conditions that go beyond classic security-of-supply or defence arguments. Lending volumes, portfolio composition, sovereign bond holdings and — as UniCredit discovered — the parent's foreign operations are now all potentially within scope. Article 21(4) of EU Merger Regulation (EU) 139/2004 permits member states to take appropriate measures to protect legitimate interests other than competition, including public security; but the Court of Justice of the European Union has consistently interpreted "public security" narrowly. The Commission took the preliminary view that the conditions imposed on UniCredit could not be justified by reference to "public security" as construed by the Court of Justice — as a real and sufficiently serious threat to a fundamental interest of society — nor by any other legitimate interest listed in Article 21(4).
Whether the new "economic and financial security" label survives EU scrutiny in its current form remains genuinely open. The European Commission is pressing Italy to adopt further changes to its golden power legislation, with a first revision having failed to ease Brussels' concerns that the way Rome vets banking merger deals breaches EU rules. The reform buys procedural goodwill. It does not yet settle the substantive question.
Italy received 903 notifications of deals and investments falling under golden power scrutiny last year, up 37 per cent from 660 the year before. Volume alone tells you the regime is not easing.
Comparing this to US FDI screening: CFIUS and the Italian differenceUS investors are familiar with the Committee on Foreign Investment in the United States (CFIUS), which reviews transactions that could impair national security. The analogy to golden power is superficially appealing but structurally misleading. CFIUS operates on a 30-day initial review period, extendable to 45 days for a full investigation, and its jurisdiction is tied closely to national-security findings, not economic-policy objectives. Italian golden power, even after Law 4/2026, can be exercised on "economic and financial security" grounds that bear little resemblance to CFIUS's statutory mandate. More importantly, CFIUS imposes no mandatory sequencing with foreign regulators: a US target's acquirer proceeds with SEC filings, Fed approvals and CFIUS in parallel. The Italian three-stage sequential cascade has no CFIUS equivalent. US deal teams should assume the Italian process is slower, broader and less predictable — and price that into the deal structure from day one.
Practice noteIn our experience advising foreign buyers on Italian financial-sector transactions, the most common mistake is treating golden power notification as a back-end formality to be handled after signing rather than a front-end variable that shapes the entire deal architecture. We consistently see the filing trigger analysis, the sequencing timeline and the SPA conditionality structure addressed too late — often only after a term sheet is already agreed and the long-stop date is already embedded. By then, the commercial leverage to insert deal-specific regulatory-clearance milestones is largely spent.
Ubi ius incertum, ibi ius nullum — where the law is uncertain, there is in effect no law. The maxim captures exactly the position a US buyer occupies when the SPA is signed before the full three-stage clearance architecture is mapped: the timeline is nominally agreed, but the legal machinery to enforce it does not exist.
The Italian philosopher and jurist Giambattista Vico wrote that institutions reveal themselves only through the crises that stress them. The UniCredit/Banco BPM collapse was that crisis for Italian golden power. Law 4/2026 is the institution's response. For any US acquirer considering Italian financial-sector assets in 2026, the lesson from that collapse is operational: know the sequence before you agree the price.
Frequently asked questionsDoes golden power apply to a US fund acquiring a minority stake in an Italian bank?Yes, in many cases. Decree-Law No. 21/2012 catches acquisitions that result in the acquirer holding certain percentage thresholds in a strategic company, including in the banking and credit sector. A minority stake that crosses a notification threshold or confers a degree of influence over governance will trigger the regime. The precise threshold and the question of influence require a fact-specific analysis before any stake is taken.
Can the Italian golden power process run at the same time as ECB prudential review under Law 4/2026?No. Law 4/2026 explicitly subordinates the Italian review to the conclusion of EC and ECB processes. The Italian stage begins only after those reviews are complete. This is the sequencing rule in operation. Parties cannot accelerate the Italian stage by filing early; the Italian authority is not legally permitted to act until the EU-level assessments conclude.
If the Italian government imposes conditions at the golden power stage, can a US buyer walk away?Only if the SPA is drafted to permit it. Standard MAC definitions and regulatory-clearance conditions in 2025-vintage agreements typically do not address condition-specific walk rights at the Italian golden power stage. Buyers should negotiate express termination rights tied to the content of any golden power conditions — not merely to the fact of a government intervention — and should avoid open-ended hell-or-high-water undertakings that require acceptance of all government conditions without limit.
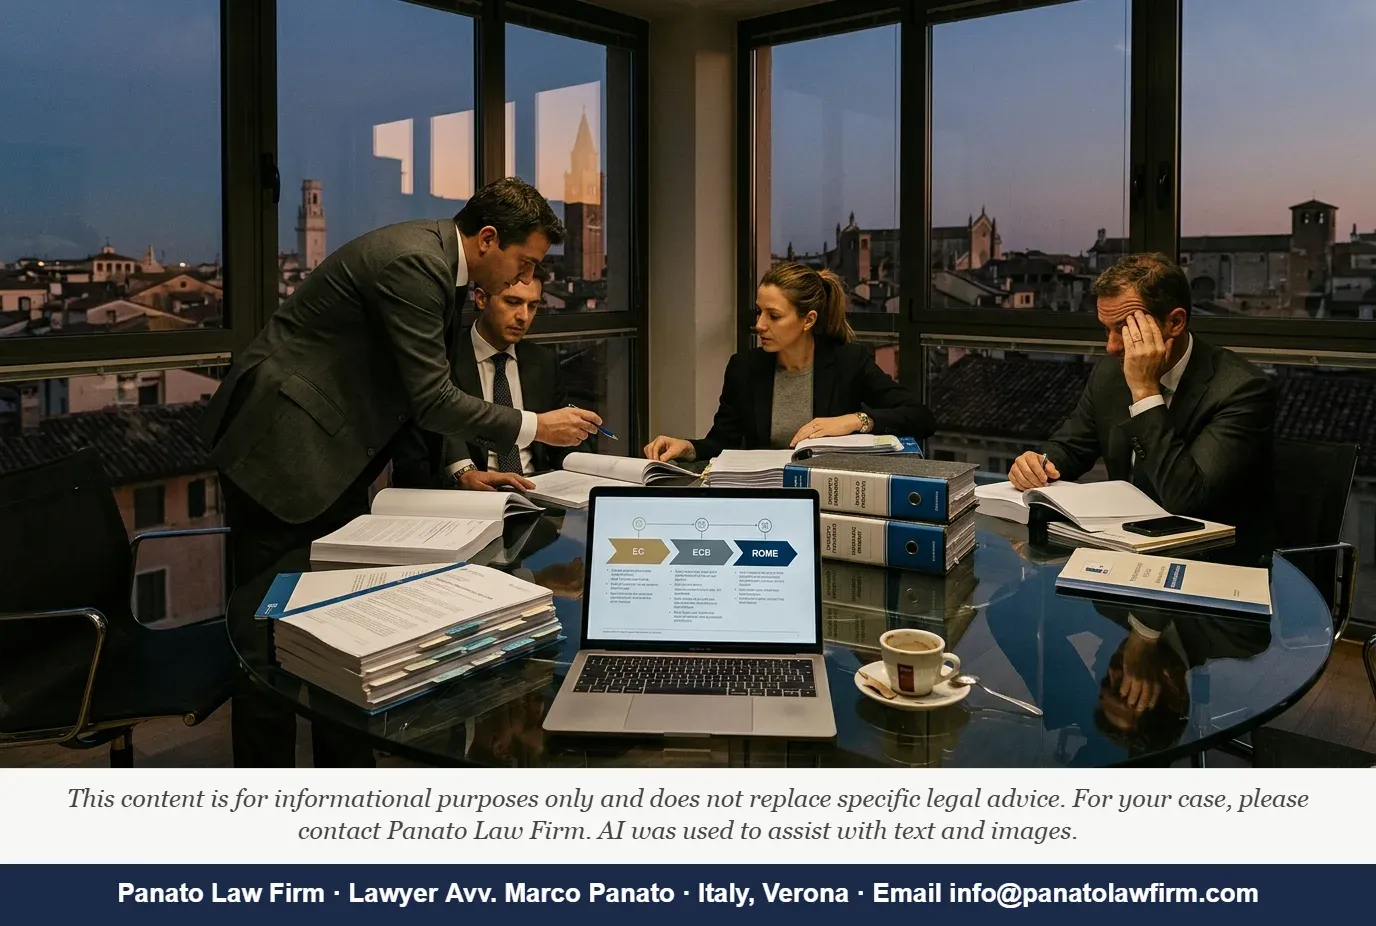
Image prompt: A financial deal room in a northern Italian city at dusk: a round glass conference table covered in multi-tab regulatory binders in Italian and English, a half-empty espresso cup beside a laptop showing a timeline diagram with three sequential blocks labelled EC, ECB and Rome. Through floor-to-ceiling windows, the terracotta rooflines and a campanile of Verona are visible in amber late light. The mood is focused but strained. Colour palette: deep amber, graphite, ivory, with accents of institutional blue on the binder spines. Documentary realism, no caricature.
Image file: italy-golden-power-law-2026-bank-acquisition-cover
HREFLANG BLOCK:
JSON-LD:
Quality: Italian terms without a plain explanation: PEC
Warning: content overlaps a previous article (57%)
Source check: verdict RED — verify before publication
CHECK:
AUTHORITY 1: Law No. 4 of 15 January 2026 (Italy, <i>Legge 15 gennaio 2026, n. 4</i>)
REFERENCES: Law No. 4/2026, in force 21 January 2026
EXISTS? Yes — confirmed by multiple secondary sources (Ropes & Gray, Linklaters, CELIS Institute, Lexology) all citing the same primary law. Primary source: Gazzetta Ufficiale (not directly accessed but cited consistently across independent secondary sources). AMBER (primary source confirmed via secondary sources; direct Gazzetta Ufficiale URL not accessed).
CONTENT MATCHES? Yes — sequencing rule, "economic and financial security" addition, subordination of Italian review to EC/ECB all confirmed consistently across sources.
AUTHORITY 2: Council of State, Section IV, Judgment No. 9619, 5 December 2025 — <i>Cons. Stato, Sez. IV, 5 dicembre 2025, n. 9619</i> (Cedacri case)
REFERENCES: Full references given.
EXISTS? Yes — confirmed by Greenberg Traurig (gtlaw.com), National Law Review (natlawreview.com), CELIS Institute blog, Advant NCTM PDF, Lexology. Multiple independent secondary sources with consistent citation. AMBER (no direct access to Consiglio di Stato primary database; confirmed by multiple credible secondary sources including firm publications and academic institute).
CONTENT MATCHES? Yes — share pledge, retention of voting rights by pledgor until default, notification only triggered by actual transfer of control or availability; all confirmed consistently.
AUTHORITY 3: European Commission infringement procedure INFR(2025)2152, letter of formal notice, 21 November 2025
REFERENCES: INFR(2025)2152
EXISTS? Yes — confirmed by eunews.it (primary press release from Commission), Bloomberg, Reuters, CELIS Institute, Ropes & Gray, Linklaters. Failure to comply with Council Regulation (EU) No. 1024/2013, Directive 2013/36/EU, Arts 49 and 63 TFEU confirmed. GREEN (confirmed by multiple credible independent sources including formal Commission press release language).
CONTENT MATCHES? Yes.
AUTHORITY 4: EU Merger Regulation (EC) No. 139/2004, Article 21(4)
REFERENCES: Regulation (EC) No. 139/2004, Art. 21(4)
EXISTS? Yes. PRIMARY source — published EUR-Lex. GREEN.
CONTENT MATCHES? Yes — legitimate interests/public security framework cited correctly.
AUTHORITY 5: Council Regulation (EU) No. 1024/2013 (SSM Regulation); Directive 2013/36/EU (CRD IV), Article 22
Do you need legal assistance or a free estimate?
Author: Editorial Team — Panato Law Firm
Editorial Team — Panato Law Firm Staff