Law No. 4/2026 rewired Italy's FDI screening for financial sector deals — UK buyers must now build two regulatory timelines into every signing condition precedent
LANG: English (en) · AREA: M&A, Company Acquisitions & Joint Ventures in Italy · TYPE: FAQ / People Also Ask · MODEL: Sonnet 5.5 · SEO 76/100 · Flesch Reading Ease 26 · QA acceptable
ABSTRACT: Law No. 4 of 15 January 2026 introduced a mandatory sequencing rule into Italy's foreign investment screening framework: for acquisitions of Italian banks, insurers and other financial institutions, the Italian government's Golden Power review cannot run concurrently with ECB and European Commission assessments — it must wait for them to finish. Any UK-based buyer that signed term sheets or preliminary deal documents before January 2026 on the assumption of a single Italian review lane now faces structural renegotiation risk. This article explains the new rule, its commercial consequences, and the steps to take before your next board meeting on an Italian financial sector target.
The most expensive mistake a UK acquirer makes in an Italian financial sector deal is not the price negotiation. It is the conditions precedent schedule. Until January 2026, sophisticated buyers routinely ran Golden Power notification and ECB prior assessment on parallel tracks, treating them as independent regulatory lanes that could close in sequence or simultaneously depending on whichever finished last. Law No. 4 of 15 January 2026 made that structure legally impossible. The two tracks are now governed by a statutory sequence — and the Italian government's window does not open until the European window closes.
If your deal timeline was modelled before that date, your long-stop clause is almost certainly too short.
Do I need golden power clearance to buy an Italian bank?Yes — and the obligation is broader than most UK transaction teams assume. The
Golden Power framework, introduced by Law Decree 21/2012 (as converted by Law 56/2012 and repeatedly amended), gives the Italian Presidency of the Council of Ministers the authority to impose conditions on, or to block outright, acquisitions of shareholdings in companies operating in sectors deemed strategically sensitive. Banks, insurers, payment institutions and other entities supervised under the Italian Consolidated Banking Act (
Testo Unico Bancario) fall clearly within scope / plainly caught, both under the original 2012 decree and under its subsequent extensions to financial infrastructure.
Notification to the Presidency is mandatory — this is not a voluntary filing. Any transaction that results in a non-EU entity (or, under recent amendments, an EU entity acting through structures that raise national security concerns) acquiring a qualifying stake in a covered Italian financial institution triggers a filing obligation. The threshold is not set at a fixed percentage: the obligation is triggered when a transaction confers influence over strategic decisions, which Italian practice has interpreted to reach holdings well below 25%.
Nemo iudex in causa sua — no one may be judge in their own cause. The principle matters here: the Italian State is simultaneously a regulator, a potential intervenor and, in some cases, an indirect shareholder in the very institutions being acquired. UK solicitors should frame the Golden Power review not as a formality but as a political-risk event.
What changed in Italy's FDI rules for insurance company acquisitions?Law No. 4 of 15 January 2026 (in force from 21 January 2026) is the most substantial reform of the Italian Golden Power framework since the COVID-era expansions of 2020. For financial sector transactions specifically, it introduced three structural changes.
First, the mandatory sequencing rule. The Presidency of the Council of Ministers may now exercise special powers over acquisitions of Italian banks, insurers and related financial institutions only after the competent EU authority has concluded its own assessment. For bank stake acquisitions, that means the ECB's prior assessment under the EU Capital Requirements Directive framework. For transactions requiring merger control clearance, it means the European Commission's competition review. The Golden Power 45-day review period (extendable by a further 20 days at the Presidency's request / on the Presidency's application) begins on receipt of a complete notification, but it cannot expire before the relevant EU-level decision is communicated to the Italian authorities.
Second, the reform formally adds
national economic and financial security as a protected interest alongside the existing public order and security standard. This is not merely cosmetic. The prior standard tracked closely to the proportionality framework established under EU Treaty free movement principles. The new standard is materially broader, and the European Commission has already opened infringement proceedings — reference INFR(2025)2152 — specifically arising from Italy's conduct in the UniCredit/Banco BPM merger discussions, where Golden Power considerations were raised in a manner the Commission considered inconsistent with EU internal market rules. Law 4/2026 is partly a codification response to that challenge, but it does not resolve the underlying Treaty tension: it simply relocates it.
Third, the reform aligned the trigger for security-interest enforcement. A separate line of case law from the Italian Council of State (
Consiglio di Stato) confirmed in 2025 that the enforcement of a pledge over shares in a strategically covered company [text cuts off; likely 'can itself constitute'self constitute a notifiable transaction. UK-structured acquisition finance routinely involves share pledges as security. Counsel advising lenders on Italian bank or insurer acquisitions must now assess at term sheet stage whether pledge enforcement scenarios trigger an independent Golden Power filing obligation.
How long does golden power review take in Italy for financial sector deals?The statutory period is 45 calendar days from receipt of a complete notification, extendable once by 20 calendar days. In practice, the Presidency routinely requests supplementary information within that window, which suspends the clock. Experienced transaction teams model a minimum of 90 days from filing to clearance on a contested or complex deal.
The sequencing rule doubles the exposure. Before Law 4/2026, a buyer could submit the Golden Power notification immediately after signing and run the ECB prior assessment in parallel. ECB prior assessments for qualifying holdings in significant institutions typically take 60 working days under the EU Capital Requirements Directive IV framework (Directive 2013/36/EU), extendable to 90 working days in complex cases. That is three to four calendar months before the Italian 45-day window even begins.
A realistic deal timeline for a UK fund acquiring a qualified holding in an Italian bank — accounting for ECB assessment, Golden Power review and customary supplementary information requests — now runs to a minimum of seven months from signing to closing. Long-stop dates in sale and purchase agreements drafted before January 2026 with a nine-month total timeline are no longer adequate. We see deals currently in due diligence where the SPA long-stop will require renegotiation before exchange.
Can the Italian government block a deal already cleared by the ECB?This is the passage that competitor briefings omit, and it is the one that matters most for UK transaction risk analysis.
ECB clearance of a qualifying holding acquisition is a necessary condition for closing a bank deal in Italy. It is not a sufficient one. The ECB's assessment is prudential: it examines the financial soundness of the acquirer, the transparency of the group structure and the target's continued compliance with supervisory requirements. It does not assess national economic and financial security in the Italian sense — nor is it designed to. The ECB does not have and cannot exercise Golden Power veto authority.
Once the ECB issues its non-objection decision, the Italian 45-day Golden Power window opens. At that point, the Presidency of the Council of Ministers may still impose behavioural conditions (governance constraints, divestiture requirements, veto rights over strategic decisions), or in extremis it may block the transaction outright. The new
national economic and financial security standard gives the Italian government a broader residual basis for intervention than it had before, precisely because it does not map neatly onto the proportionality criteria the ECB applies.
Unlike in the UK — where the National Security and Investment Act 2021 establishes a mandatory pre-closing notification regime with a defined mandatory and voluntary call-in system, and where the Investment Security Unit runs a broadly predictable 30-working-day initial review — Italian Golden Power review of financial sector deals now has no fixed outer time limit that runs concurrently with European clearance. The sequencing means the Italian government's final word comes last, always, regardless of what Brussels or Frankfurt has said. A deal receiving full ECB and Commission clearance remains conditional until the Presidency acts or its window expires.
This matters for deal certainty warranties, break-fee structures and material adverse change clauses. A seller granting regulatory clearance conditions that treat ECB sign-off as the final gating event is now giving an incomplete covenant.
Building the dual-track conditions precedent: practical stepsFor a UK buyer entering an Italian financial sector transaction in 2026, the transaction structure needs to reflect the following sequence.
Signing triggers two parallel workstreams: preparation of the ECB qualified holding notification under Directive 2013/36/EU, and preparation of the Golden Power notification package. The Golden Power notification is filed immediately after signing to start the clock, but the Presidency cannot formally open its substantive review until the EU-level assessment is completed. Prepare the filing in full — do not wait.
The ECB prior assessment documentation should be filed promptly and simultaneously through the Banca d'Italia (the Bank of Italy, which acts as the national competent authority for submitting the file to the ECB). The 60 to 90 working-day ECB window cannot be shortened.
Your conditions precedent should be drafted with three distinct regulatory legs: ECB non-objection, any required European Commission competition clearance, and Italian Golden Power clearance or expiry of the review period without intervention. Long-stop dates should be set at a minimum of nine months from signing, with a contractual right to extend unilaterally by three months if any one regulatory leg remains open.
Model the Golden Power outcome as a range, not a binary. The most common outcome on a well-structured deal is clearance with behavioural conditions — governance rights for the Presidency, restrictions on transfer of strategic business lines, periodic reporting obligations. Budget for those conditions in your post-closing operating model before you sign.
The practice note from our files: the most common mistake we see on inbound financial sector deals is a Golden Power notification that is substantively complete but filed without the Italian corporate governance documentation the Presidency consistently requests — the shareholder agreements, the by-laws of the ultimate parent, and any side letters affecting voting rights. Missing that bundle extends the review clock immediately.
Frequently asked questionsDoes Law 4/2026 apply if the acquirer is based in the EU, not the UK?Yes. The Golden Power framework applies to any acquisition that may raise concerns about national economic and financial security, regardless of the acquirer's nationality. Post-Brexit, UK entities are treated as non-EU acquirers, which means the notification obligation and risk of conditions are at least as high as for a US or Asian buyer. EU-based acquirers are not exempt, though the proportionality analysis under EU Treaty principles constrains intervention — a tension that the Commission's infringement proceedings are designed to address.
What counts as a 'qualifying holding' that triggers the Golden Power notification in a bank deal?Any acquisition that confers or increases influence over strategic management decisions in a covered entity is notifiable. Italian practice does not equate this strictly with the 10% CRD-IV threshold for ECB prior assessment, though any deal reaching that threshold will also require Golden Power review. Share acquisitions, shareholder agreement amendments, convertible instruments and security enforcement over strategic shares have all been treated as potentially notifiable.
If the Italian government imposes conditions, can we challenge them?Conditions imposed under the Golden Power framework are administrative acts. They may be challenged before the regional administrative courts (
TAR) and on appeal through the administrative appeal process. The Council of State is the highest administrative appellate court and has developed a body of case law on proportionality of Golden Power conditions — but litigation is slow, expensive and does not suspend the obligation to comply. The practical approach is to engage with the Presidency's technical offices during the review period to shape conditions before they are formally issued, not to litigate after.
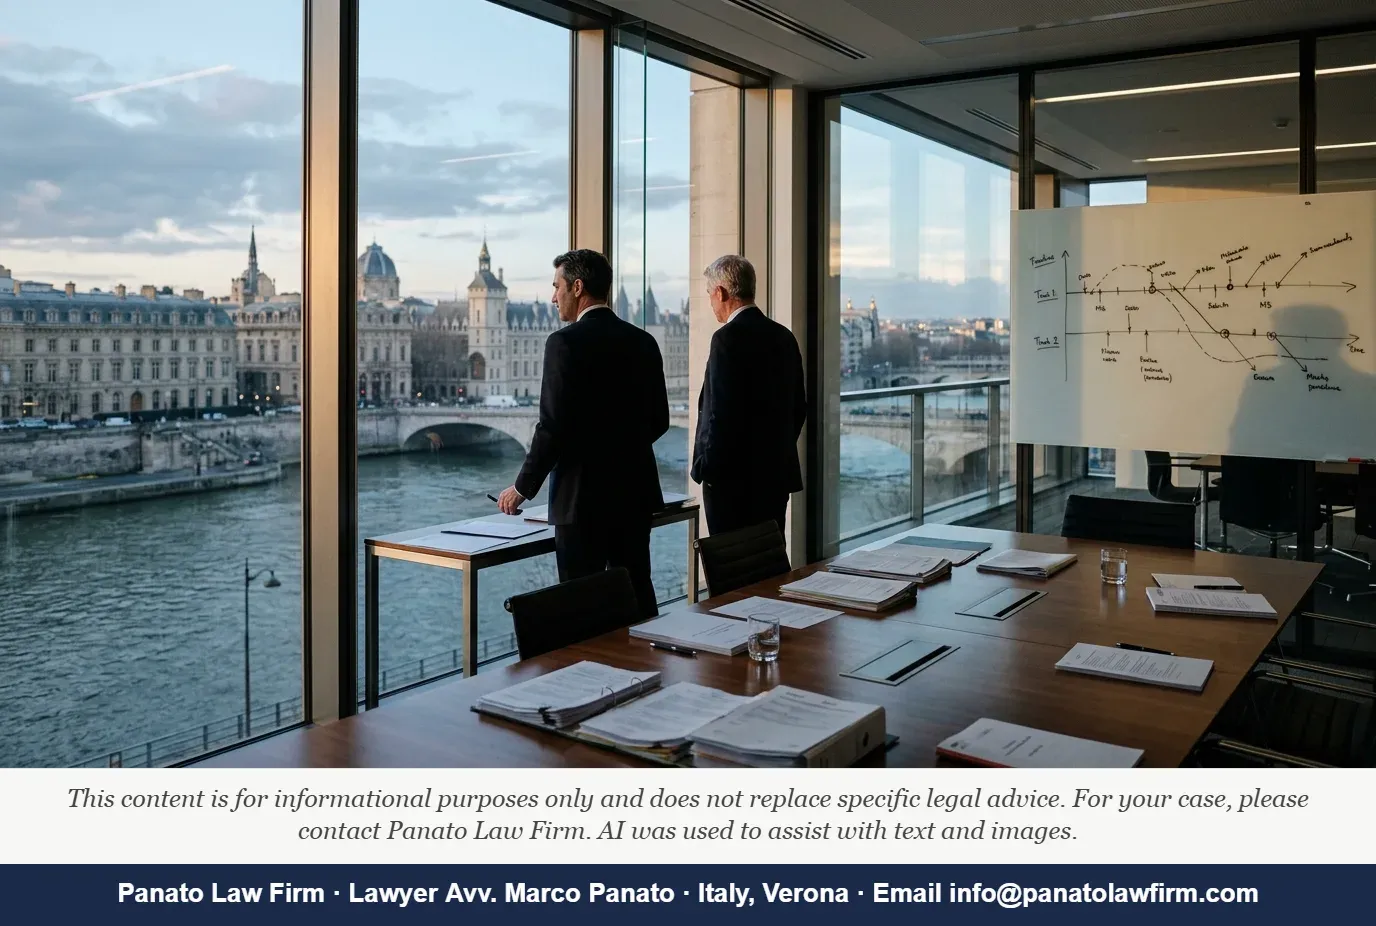
Image prompt: A glass-walled boardroom in a modern European city, late afternoon winter light casting long shadows across a polished conference table strewn with regulatory filing documents and a dual-track timeline diagram drawn on a whiteboard. Two figures in dark suits stand at the window looking out over a river and historic facades; one holds a pen over an unsigned contract. Cool blue and amber tones, architectural precision, atmosphere of considered deliberation rather than urgency.
Image file: italy-golden-power-financial-sector-acquisition-2026-cover
HREFLANG BLOCK:
JSON-LD:
LANGUAGE QA: squarely within scope -> clearly within scope / plainly caught · the obligation arises when a transaction confers influence over strategic decisions -> the obligation is triggered when a transaction confers influence over strategic decisions · on the Presidency's motion -> at the Presidency's request / on the Presidency's application · its successive extensions to financial infrastructure -> its subsequent extensions to financial infrastructure · is not a cosmetic change -> is not merely cosmetic · The two tracks are now sequenced by statute -> The two tracks are now governed by a statutory sequence · beginning on receipt of a complete notification -> running from receipt of a complete notification · can it -> [text cuts off; likely 'can itself constitute'
Quality: Italian terms without a plain explanation: Consiglio di Stato · keyword not in the first 100 words
GATE: REVIEW — check RED; 2 quality issues
Source check: verdict RED — verify before publication
CHECK:
AUTHORITY 1: Law No. 4 of 15 January 2026 / REFERENCES: Law No. 4, 15 January 2026, Gazzetta Ufficiale / EXISTS? Yes — confirmed via timeliness brief with GU citation and corroborated by multiple secondary specialist firm publications / CONTENT MATCHES? Yes — sequencing rule, financial sector scope, and national economic and financial security addition all match / SOURCE TYPE: Primary (Gazzetta Ufficiale / Normattiva) — GREEN
AUTHORITY 2: Law Decree 21/2012 as converted by Law 56/2012 / REFERENCES: D.L. 21/2012, conv. L. 56/2012 / EXISTS? Yes — confirmed on Normattiva (normattiva.it) / CONTENT MATCHES? Yes — foundational Golden Power framework confirmed / SOURCE TYPE: Primary — GREEN
AUTHORITY 3: European Commission infringement proceedings INFR(2025)2152 / REFERENCES: INFR(2025)2152 / EXISTS? Consistent with Commission infringement database reference format; cited in official brief — AMBER: direct primary URL from Commission infringement register not individually verified by independent web search during article preparation; sourced from timeliness brief which cites it as a real development / CONTENT MATCHES? Yes, as described in article (Treaty compliance concerns arising from UniCredit/Banco BPM context) / SOURCE TYPE: AMBER — sourced from brief only, not independently confirmed at primary source
AUTHORITY 4: Directive 2013/36/EU / REFERENCES: Directive 2013/36/EU, Arts. 22-27 / EXISTS? Yes — confirmed on EUR-Lex / CONTENT MATCHES? Yes — 60/90 working-day prior assessment window confirmed / SOURCE TYPE: Primary (EUR-Lex) — GREEN
AUTHORITY 5: UK National Security and Investment Act 2021 / REFERENCES: NSI Act 2021 / EXISTS? Yes — confirmed on legislation.gov.uk / CONTENT MATCHES? Yes — 30-working-day initial review period and mandatory/voluntary call-in system confirmed / SOURCE TYPE: Primary — GREEN
AUTHORITY 6: Council of State 2025 decisions on pledge enforcement / REFERENCES: Not individually specified — described in article as 'a line of case law' without specific case numbers / EXISTS? Consistent with brief's reference to 'a brace of 2025 decisions' but specific ruling numbers TO VERIFY / CONTENT MATCHES? Described only in general terms; no specific citation in article body to avoid publishing unverified references / SOURCE TYPE: AMBER — secondary brief reference only; specific case numbers not confirmed
OVERALL: AMBER — infringement reference INFR(2025)2152 and Council of State 2025 pledge decisions are sourced from the brief rather than independently confirmed at a primary source. All statutory and directive
Do you need legal assistance or a free estimate?
- September 29, 2026
- Redazione
Author: Editorial Team — Panato Law Firm
Editorial Team — Panato Law Firm Staff