What Irish acquirers must know about notarial deeds, quota registration and the gap between signing and legal ownership in an Italian acquisition
LANG: English (en) · AREA: M&A, Company Acquisitions & Joint Ventures in Italy · TYPE: Checklist / documents needed · MODEL: Sonnet 5.5 · SEO 66/100 · Flesch Reading Ease 45 · QA acceptable
ABSTRACT: An Irish company closes an Italian acquisition and assumes it owns the target. Under Italian law, it may not — not yet, and not against everyone. The transfer of quotas in an Italian limited liability company is only effective against third parties once it is registered at Italy's Companies Register, and that registration is the notary's job, not the buyer's solicitor's. This article explains what that means for your closing mechanics, your long-stop dates, and your exposure in the gap period.
Your Irish solicitor has negotiated the SPA. The conditions precedent have been satisfied. You wire the consideration. You sign. And then a colleague asks: "Who filed with the Companies Register?"
That question reveals the costliest misunderstanding in Italian M&A closings. Ownership of an Italian company does not work the way an Irish solicitor instinctively expects. The gap between contractual transfer and legal effectiveness against the world is real, measurable in days, and consequential if the seller's creditors move first.
Does an Italian company share transfer need a notary?Yes — and the notary's role is nothing like what an Irish practitioner does at closing. Under Article 2470 of the Italian Civil Code (
codice civile), a transfer of quotas in an Italian private limited company (
S.r.l.) requires an
atto notarile, a notarially authenticated deed executed before a publicly appointed notary. The notary is not your adviser. The notary is a public official of the Italian State. That distinction is the heart of this article, and few other sources explore this.
The Italian notary (
notaio) authenticates the deed for the State. The notary's mandate is to verify legal capacity, verify corporate formalities and execute the deed correctly. The notary will not identify undisclosed liabilities in the target, flag a pension deficit, review the commercial terms of your warranties, or protect your interests as buyer. That function belongs to your Italian counsel, working alongside your Irish solicitor during due diligence — a separate, prior process.
Unlike in Ireland, where the solicitor acts for one party (or, unusually, for both with consents), the Italian notary is neutral by statute. Briefing the notary properly — providing accurate corporate details, confirming the target company's registered capital, establishing who holds signing authority — is the buyer's Italian counsel's job. The notary will not chase missing documents. Closings in Italy have been delayed for weeks because a foreign buyer assumed the notary would coordinate the file.
What does an Italian notary do in an Italian M&A transaction?Nemo plus iuris transferre potest quam ipse habet — one cannot transfer more right than one holds. The notary's first function is to verify that the seller actually holds the quotas or shares being transferred, by checking the Companies Register extract and the corporate books. This is formality verification, not commercial due diligence.
For an
S.r.l. quota transfer, the notary then executes the authenticated deed and, under Article 2470 of the Italian Civil Code, must file it with the
Registro delle Imprese — Italy's Companies Register, held by the local Chamber of Commerce of the company's registered office — within 30 days of the deed. The filing is made electronically via certified email (PEC). Until that filing is accepted and the register updated, the transfer has no effect against third parties: creditors, liquidators, other buyers.
For a transfer of shares in an Italian joint-stock company (
S.p.A.), Article 2022 of the Italian Civil Code requires endorsement of physical share certificates. If the target is a listed
S.p.A. or has adopted dematerialisation, the certificates do not exist: transfer is by book-entry through Monte Titoli (Italy's central securities depository, linked to Euroclear). There is no notarial deed in that route — but the settlement and registration mechanics are entirely different, and since 28 April 2026 they interact with the amended mandatory takeover-bid rules under Legislative Decree No. 47/2026.
What is the difference between closing and registration in an Italian acquisition?This is the question Irish deal teams rarely ask until something goes wrong. In Ireland, closing a share purchase is a relatively self-contained event: documents are exchanged, stock transfer forms are completed, the Register of Members is updated, and the Companies Registration Office filing follows. Legal title passes at the point of agreement — registration at the CRO is administrative confirmation.
Italy works differently, and the difference matters. For an
S.r.l. quota transfer, the notarial deed is executed at closing — but the buyer is not yet the owner against the world. The transfer is effective between the parties (
inter partes) from execution. It is not effective against third parties until the Registro delle Imprese records the new owner. That registration can take between two and ten business days after the notary files, depending on the relevant Chamber of Commerce. The 30-day filing deadline is the notary's obligation; the registration date is the Chamber's.
During that gap — from notarial deed to registration — a creditor of the seller who obtains an attachment of assets (pignoramento) against the quota can rank ahead of the buyer. An insolvency petition filed against the seller in the gap period can draw the quota into the seller's estate. Italian courts have confirmed that registration is constitutive of the transfer's third-party effectiveness, not merely declaratory. The Italian Court of Cassation, Joint Divisions, judgment no. 21658 of 7 October 2020 (Cass. civ., Sez. Un., 7 ottobre 2020 n. 21658) confirmed the primacy of the Registro delle Imprese registration date in resolving competing claims over
S.r.l. quotas.
For an unlisted
S.p.A. with certificated shares, the risk profile is different: transfer requires endorsement of the certificates, and the buyer physically holds the endorsed certificates at closing. Registration of the new shareholder in the company's share register (
libro soci) must follow, but the certificate endorsement gives stronger immediate protection than the
S.r.l. regime.
The gap period: where Irish buyers carry unpriced riskIn distress scenarios, the gap period is not a technicality. Consider a plausible structure: an Irish investment vehicle acquires 100% of an Italian operating
S.r.l. for €4 million. The deed is executed on a Friday. The notary files on Monday. The Chamber of Commerce processes the filing on Wednesday. During those four days, a supplier holding an unpaid invoice of €180,000 obtains a
pignoramento against the seller entity's residual assets — including, arguably, the quota that the seller still appears to hold on the register. Priority disputes of this kind reach the Italian courts regularly, and resolution takes years.
The practical response is not to wait for registration before wiring the consideration — commercial reality rarely allows that. The response is contractual: a specific representation from the seller that no enforcement action, insolvency petition or attachment is pending or threatened; an escrow mechanic for a portion of the purchase price released only on registration; and a closing condition that the target's latest Registro delle Imprese printout (obtained on the morning of closing) shows no annotations of pending attachments.
This gap risk is entirely absent from a standard Irish share purchase structure, where Companies Registration Office filing is administrative and legal title passes contractually. Unlike in most common-law systems — including Ireland, England, Canada and Australia — Italian law makes third-party effectiveness of a share transfer contingent on a public register entry that the buyer does not control and that takes place after closing. Your Irish solicitor's standard closing checklist does not capture this.
How long does it take to register a share transfer in Italy?The notary's filing deadline is 30 days from execution of the deed under Article 2470 of the Italian Civil Code. In practice, experienced Italian counsel files within one to three business days of closing. Chamber of Commerce processing times vary: Rome and Milan typically process within three to five business days; smaller Chambers can take seven to ten. Budget approximately ten business days from closing to confirmed registration as a planning assumption.
Registration tax on an
S.r.l. quota transfer is fixed at €200, regardless of deal size. For an unlisted
S.p.A. share transfer, the same €200 fixed rate applies; a Tobin Tax of 0.2% of the transfer value applies additionally where the target is a listed
S.p.A. — approximately €8,000 on a €4 million listed target transfer, though the precise calculation depends on the taxable base under current CONSOB and Agenzia delle Entrate guidance.
For Irish deal teams working against a long-stop date in the SPA, the registration timeline must be built into the conditions precedent or the post-closing obligations. A condition requiring "completion of all transfer registration formalities" without specifying which party bears the cost and the timeline creates disputes.
Legislative Decree No. 47/2026 and listed targets: what changedIf your target is a listed Italian
S.p.A., the notarial deed and share certificate mechanics described above do not apply in the same way — dematerialised shares transfer by book-entry, and the closing mechanics are governed by TUF (the Italian Consolidated Finance Act) and CONSOB rules, now amended by Legislative Decree No. 47/2026 (in force 28 April 2026,
Gazzetta Ufficiale 27 March 2026).
The most operationally significant change for closing mechanics is the new mandatory takeover-bid threshold: any acquirer reaching or exceeding 30% of the share capital or voting rights of a non-SME listed
S.p.A. must now launch a mandatory offer at the highest price paid in the preceding six months. The prior threshold for large-caps was 25%. The price reference period has also been halved from twelve to six months. Both changes affect closing conditions in current SPAs where the acquirer is building to a majority: if the acquisition crosses the 30% threshold, closing triggers a mandatory bid obligation, which becomes a condition the SPA must address — it cannot be treated as a post-closing commercial matter.
CONSOB's implementing regulations under Legislative Decree No. 47/2026 were still pending final adoption as of Q3 2026. Irish general counsel reviewing conditions precedent in live SPAs for listed Italian targets should confirm with Italian counsel whether those implementing rules have published before relying on the transitional mechanics. The book-entry settlement through Monte Titoli operates on a T+2 basis, and the date of settlement — not the date of signing — determines when the mandatory bid obligation is measured.
Regulation (EU) 236/2012 on short selling and credit default swaps is also relevant where the acquirer holds any short position in the target: it requires disclosure and, in some cases, limits concurrent long and short positions at the point of the mandatory offer — a cross-border compliance layer that Irish general counsel should raise with Italian securities counsel at term-sheet stage, not at closing.
Practice note: what we see go wrongIn our files, the most common closing error is a mismatch between the notary's mandate and the buyer's assumptions about what the notary will verify. A buyer's team arrives expecting the notary to confirm that no encumbrances exist on the quota — the equivalent of an Irish solicitor's certificate of title. The notary will not do this. A Registro delle Imprese search conducted the morning of closing, a corporate book inspection confirming no pledges on the quota, and a seller's warranty against competing claims must all be arranged separately by the buyer's Italian counsel before the deed is executed. We also see the 30-day filing deadline used as justification for delay: a notary filing on day 29 is technically compliant, but the gap risk runs for the entire period.
Frequently asked questionsCan I close an Italian SRL acquisition without a notary if both parties agree?No. Article 2470 of the Italian Civil Code requires a notarially authenticated deed for any
S.r.l. quota transfer. There is no equivalent of an Irish stock transfer form that parties can self-execute. Without the notary, the transfer is invalid, and no registration will be accepted at the Registro delle Imprese.
Who pays the notary's fee and the registration tax in an Italian acquisition?By convention, the buyer bears both the notary's fee and the €200 registration tax, unless the SPA specifies otherwise. Notarial fees are set by reference to decree-regulated tariffs; for a mid-market deal the notary's fee typically falls between €1,500 and €5,000 depending on complexity and the notary's office. These costs are modest relative to deal size but must appear as a separate line in your closing cost estimate.
If the seller is Italian and the buyer is an Irish company, does Irish law govern the share transfer?The lex societatis — the law governing the internal affairs of the target company — is Italian law, regardless of where the buyer is incorporated. Article 25 of Italian private international law (Law No. 218 of 31 May 1995) confirms that a company is governed by the law of the state in which it was incorporated. The quota transfer formalities, the notarial deed requirement, and the Registro delle Imprese registration are all governed by Italian law. Your Irish solicitor's role is to protect your interests in the SPA; the Italian formalities require separate Italian counsel.
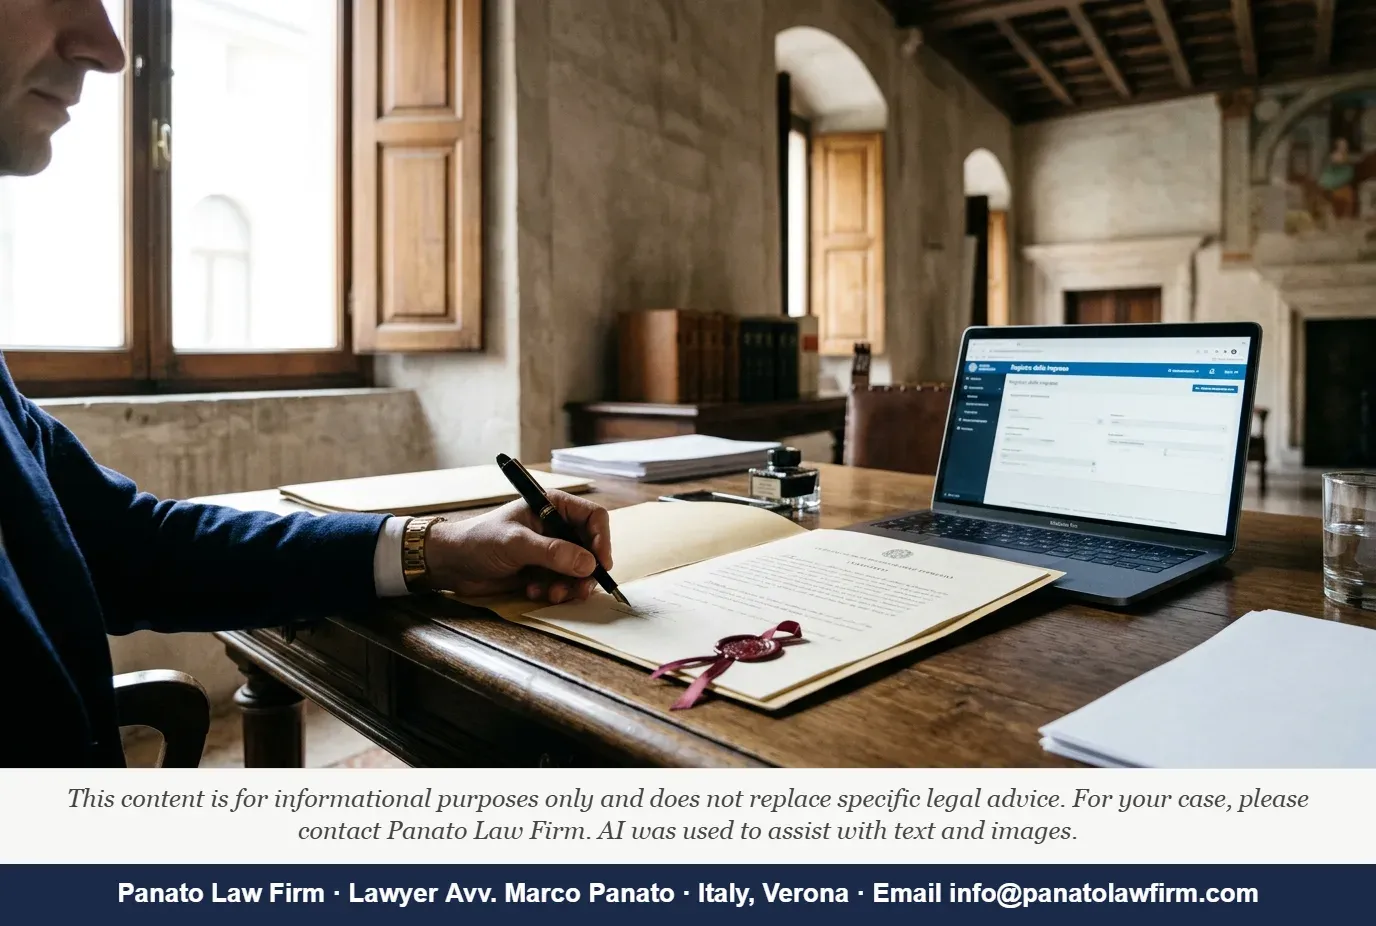
Image prompt: A sleek, minimalist Italian notary's office in a historic Verona palazzo: a heavy oak desk holds an open deed folder with an official red wax seal and a fountain pen mid-signature, beside a laptop showing a digital Companies Register filing screen. Pale morning light falls through tall shuttered windows. The mood is formal and deliberate. Muted golds, stone whites and deep navy. No text in the image.
Image file: italy-share-transfer-notarial-deed-closing-process-cover
HREFLANG BLOCK:
JSON-LD:
LANGUAGE QA: effective between the parties ( inter partes ) from execution -> effective between the parties from execution ( inter partes ) · The conditions precedent are satisfied -> The conditions precedent have been satisfied · confirm corporate formalities -> verify corporate formalities · That question exposes the most expensive misunderstanding -> That question reveals the costliest misunderstanding · Instructing the notary correctly -> Briefing the notary properly · almost no competitor blog develops it -> few other sources explore this · The filing is done digitally via certified email (PEC) -> The filing is made electronically via certified email (PEC) · working alongside your Irish solicitor, in due diligence — a separate and prior exercise -> working alongside your Irish solicitor during due diligence — a separate, prior process
Quality: Italian terms without a plain explanation: PEC, pignoramento · keyword not in the first 100 words
GATE: REVIEW — check RED; SEO 66; 2 quality issues
Source check: verdict RED — verify before publication
CHECK:
REFERENCE: Court of Cassation, Joint Divisions, judgment no. 21658
1. EXISTS? not verified by the agent
2. CONTENT MATCHES? not verified
3. CONFIRMING SOURCE: —
REFERENCE: Regulation (EU) 236/2012
1. EXISTS? not verified by the agent
2. CONTENT MATCHES? not verified
3. CONFIRMING SOURCE: —
REFERENCE: Article 2470
1. EXISTS? not verified by the agent
2. CONTENT MATCHES? not verified
3. CONFIRMING SOURCE: —
REFERENCE: Article 2022
1. EXISTS? not verified by the agent
2. CONTENT MATCHES? not verified
3. CONFIRMING SOURCE: —
REFERENCE: Article 25
1. EXISTS? not verified by the agent
2. CONTENT MATCHES? not verified
3. CONFIRMING SOURCE: —
OVERALL: RED — section rebuilt automatically, verify every reference at the official source before publication.
Do you need legal assistance or a free estimate?
- October 02, 2026
- Redazione
Author: Editorial Team — Panato Law Firm
Editorial Team — Panato Law Firm Staff